You want progress, but budgeting feels like punishment
It usually starts right after a “good” paycheck. You mean to get ahead this month, but the timing is ugly: a birthday dinner, a car registration renewal, and a couple of workdays where takeout feels like the only thing keeping you functional. By the time you open your budgeting app, it’s already telling you “no” more than it’s telling you anything useful. The plan might be reasonable on paper, but it lands like punishment in real life—especially when your income is steady and the leaks are small, frequent, and tied to convenience.
What trips most people up isn’t math, it’s the emotional rhythm. Budgets tend to treat every “extra” dollar as a mistake, even when that spending is buying time, energy, or a little relief. So you tighten up for a few days, feel deprived, then rebound with a bigger swipe that wipes out the week. The result is this nagging uncertainty: are you actually undisciplined, or is the system just designed in a way you won’t stick to?
If budgeting feels like getting grounded, the fix usually isn’t more restriction—it’s a different feedback loop. Before changing categories or cutting subscriptions, it helps to admit what you’re chasing: visible progress you can feel in the middle of the month, not just at month-end. That’s where playful tracking starts to matter, because it gives you a reason to keep showing up even when the calendar throws expensive surprises at you.
Turn saving into a points game with rewards
Instead of trying to “behave” for 30 straight days, give yourself something to score. Pick 3–5 actions that actually move money—packing lunch, skipping a rideshare, cooking once, transferring $25, selling something—and assign points based on difficulty. Keep it slightly unfair on purpose: the actions you avoid most should earn more. The constraint is real here: points can’t require extra spending, or the game just becomes another leak.
Then set a weekly points target that fits your calendar. If you’ve got a wedding and a busy work week, the target drops, not your self-respect. Rewards need rules too: small, planned, and capped (a $10 coffee, a movie rental, one guilt-free convenience meal). If you miss the target, you don’t “pay” for it—you just don’t unlock it.
The weird part is how quickly this changes the middle-of-the-month mood. You’re not staring at categories you already “blew.” You’re stacking wins, and the savings transfer starts to feel like the highest-scoring move on the board.
Use challenge weeks to reset spending habits
Once the points start working, you’ll notice another pattern: some weeks are just noisier than others. A “normal” week can handle a couple of wins. A chaotic one turns every small decision into an expensive shortcut. That’s when a challenge week helps—not as a new lifestyle, but as a clean reset that’s short enough to tolerate.
Pick one five-to-seven-day constraint that matches the leak you’re trying to patch. A “no takeout” week, a “cash-only for fun” week, or a “no Amazon” week all work because the rule is simple at the register. The catch is timing: don’t schedule it during travel, deadlines, or family events, or you’ll fail for reasons that have nothing to do with spending.
Give the week a job. Decide where the money goes as it’s “saved”—straight to a transfer, a debt payment, or a specific sinking fund. If the challenge creates a rebound day afterward, cap it in advance (one planned convenience meal), so the reset doesn’t turn into payback.
Create a visual progress wall you actually update
After a challenge week, the slippery part is what happens when life goes back to normal. The momentum fades because the progress disappears into an account balance you only check when you’re already stressed. So give the progress somewhere to live that you’ll see when you’re about to make the “small” purchase that quietly resets your month.
Pick one goal and make it visible: a thermometer you color in, a chain of boxes you check, or a sticky-note ladder on the fridge. Tie it to a real number—$1,000 emergency buffer, $2,400 credit card payoff, $600 for a weekend trip—and break it into chunks you can realistically hit (like $25 or $50). If the chunks are too big, you’ll avoid updating it after an expensive week.
Then set a rule for updates that fits your timing constraint. I like “update only on transfer days,” because it keeps the wall honest and stops the temptation to “count” good intentions. When the wall starts filling, you’ll catch yourself wanting the next square more than the impulse buy, which is the whole point of making it physical.
Automate tiny transfers, then compete with yourself
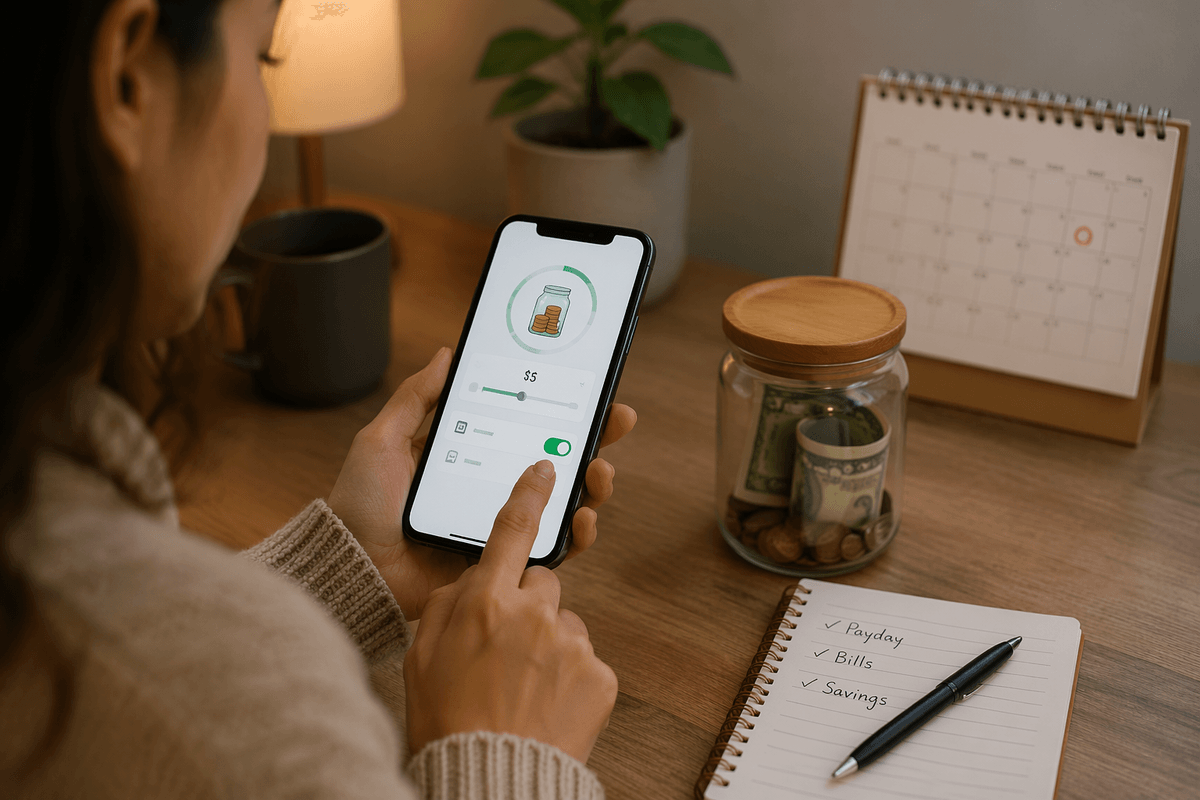
Once the wall is up, the next annoyance shows up fast: you can’t win a month on motivation alone. Some weeks you’ll forget, other weeks you’ll “wait until things calm down,” and the calm never arrives. So you take the decision out of it. Set an automatic transfer that’s almost insulting—$5 a day, $20 every Monday, or 1% of each paycheck—aimed at one named goal account. The constraint is cash-flow timing: schedule it for the day after payday, not the day before autopay bills hit.
After two or three weeks, the game shifts from “did I save?” to “can I beat last month without noticing?” Keep the automation, then add a personal best: once a week, manually top it up by a tiny amount tied to real behavior—round up yesterday’s spending, add the cost of one skipped takeout, or toss in any cash-back. If a tight week happens, the rule is simple: automation stays, the extra is optional.
Try a barter-and-swap month for one category
After a month or two of tiny transfers, the next itch is novelty. The wall is filling, but spending still shows up in the same places—especially the category that feels “small” until it’s suddenly not. So for one month, pick a single lane to experiment with: clothes, kids’ gear, books, hobby supplies, basic home items. Not groceries, not utilities. Keep the constraint tight because time is the hidden cost here; if the swap hunt takes five hours, it’s not a win.
Set rules before you start: a dollar cap for any “top-up” (like $20 if the swap isn’t exact), and a quality standard so you don’t drag home junk that creates future spending. Use Buy Nothing groups, neighborhood chats, and one-off swaps with coworkers. When you want to buy, you trade first, then decide if it’s still worth cash. The surprise is how often the urge passes once you’ve done the work.
At the end of the month, transfer the “would’ve spent” estimate into the same goal account. Even if it’s imperfect, it turns creativity into measurable progress instead of another cute experiment.
Money dates with friends—fun, but risky
After a barter month, the next temptation is to make it social. You tell a friend you’re “trying to be better with money,” and suddenly there’s accountability that doesn’t feel like an app judging you. A money date can work the same way a gym buddy works: it gets you to show up on the days you’d rather ignore the numbers.
Keep it light and specific. Meet for a cheap coffee and bring one thing: a single goal and one metric (credit card balance, emergency fund dollars, or “days I brought lunch”). The constraint is time—set a hard 30 minutes—so it doesn’t turn into a therapy session that ends with an expensive dinner.
The risk is comparison and oversharing. Don’t trade salaries, don’t “confess” every purchase, and don’t take their system as a verdict on yours. If the check-in leaves you feeling behind, switch the script: compare actions taken, not totals, and agree on one small challenge for the next two weeks.
Run a playful monthly review, not a spreadsheet marathon
By the time the month ends, the last thing you want is an hour of receipts and guilt. So keep the review short enough that you’ll actually do it—15 minutes, timer on, on the same night your rent or mortgage clears. The constraint is energy: if it requires “focus time,” it won’t happen after a long workday, and then the next month starts with the same fog.
Pull up one screen: your checking account and the one goal account you’ve been feeding. Ask three questions only: What moved me forward? What quietly drained me? What surprised me? Circle one leak to play with next month (late-night delivery, random Amazon add-ons), and pick one counter-move (a challenge week, a points target, or a slightly higher auto-transfer).
Then close it with a small win you can see. Update the wall, write your “personal best” number on a sticky note, and choose one pre-approved treat for staying in the game. The review isn’t for perfection—it’s to leave the month with a plan that feels doable.